




A charitable lead trust (CLT) is set up by you and pays income to NewYork-Presbyterian for a number of years. At the end of the trust term, the principal can be paid to you, another person, or a non-charitable entity. A CLT may provide you with substantial tax benefits while supporting the vital work of NewYork-Presbyterian.
CLTs provide distinct benefits:
- A CLT may allow you to make a transfer of assets to your heirs at a substantially reduced gift and estate tax cost, or
- It may provide you with substantial income tax benefits in the year of a windfall, a one-time increase in taxable income, such as a taxable payout or the sale of a business.
Either type of CLT provides an income stream to NewYork-Presbyterian for a set period of time that you choose. At the end of the trust term, the trust principal is either passed to your heirs or to a trust for their benefit or is returned to you and may provide you with a substantial income-tax deduction in the year of the windfall.
How You Can Establish a CLT
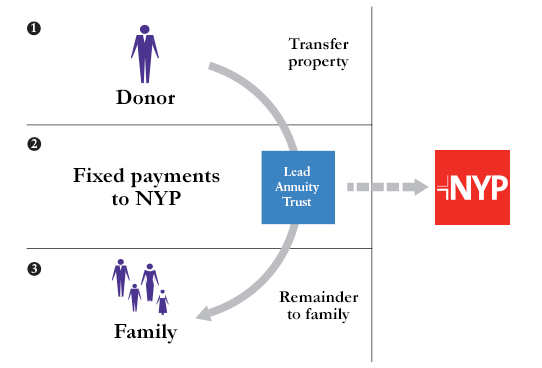
- You transfer cash, securities, or other property to a trust.
- During its term, the trust pays a fixed amount each year to NYP.
- When the trust ends, its remaining principal passes to you, your family, or other heirs you name. Trust growth distributed to your heirs may pass to them tax-free.
You can establish a CLT with publicly traded securities, closely held stock, income-producing real estate, partnership interests, or a combination of the above. You may receive the most favorable capital gains tax treatment if you fund the trust with cash or non-highly appreciated assets. Typically, a CLT is most effective if you fund the trust with assets valued at $1,000,000 or more.